Grew the number of users who complete a quote by three times. One screen got cut before it could scale to everyone.

Only 21 out of every 100 people who started ACKO's new car insurance flow finished getting a quote. I needed to know why the other 79 left.
Half of them were still researching. Their car wasn't arriving for weeks, so there was no rush to buy insurance yet. The other half had already been talked out of it by a dealer. One buyer mentioned ACKO to his dealer while picking up his car. The dealer dropped the price from one lakh rupees to thirty five thousand on the spot, not because ACKO was too expensive, just to keep the sale.
I rebuilt the journey around three calls. Speak up directly against what dealers were telling buyers, instead of staying neutral. Split the experience based on how close someone was to actually buying. Test every change on real users before rolling it out to everyone. Three releases over three months took entry to quote from 21% to 65%.
The early numbers looked like a funnel problem. Entry to quote sat at 44% overall, 66% once you removed accidental taps. But the real story was underneath those numbers.
Two signals made this clear. Same day buyers converted quote to sale 11% of the time. Buyers who weren't sure yet converted quote to sale half a percent of the time. That gap is twenty times wide, and no amount of streamlining the steps closes it. Half of every quote came from people whose car was still weeks away. That's the biggest group of users, and almost none of them converted. Nothing in the journey gave them a reason to act early.
I needed the product to do three things the old journey couldn't. Each became a structural decision, not a screen level fix.
The product needed to stand for something specific. Confident, fact led, activist, not defensive. Named dealer claims, real settlement data, specific not generic.
A user who hasn't booked yet needs a different product than someone picking up tomorrow. One booking status screen, three flows not one, routed by how close they are to buying.
A prototype can't tell you 99% of users will ignore your landing page. 1% of real traffic can. Roll out in stages, test each release with a clear question, cut what doesn't work.
User enters the new car insurance journey, picks booking status (booked / finalised but not booked / still deciding), then follows one of three paths:
| Path | What they get |
|---|---|
| Booked | Straight to make, model, variant, then plans. Get out of the way and route them to buy. |
| Finalised | Lock in incentive first. Give them a reason to commit before the dealer visit. |
| Deciding | Education and comparison. Build intent. No pressure to buy. |
One screen, asking where someone was in the buying process, became the spine of the new journey. Every screen after it was built around what the user told us there.
Three decisions that shaped the journey. Each pushback changed something structural. The first set up the tone, the second set up the architecture, the third caught what would have scaled badly.
Answered dealers head on, not politely
The call. Early drafts stayed neutral. That doesn't work on someone standing in a showroom being told the opposite. I named real garages, showed real settlement numbers, answered dealer claims directly.
Split the flow by how close someone was to buying
The call. A user who hasn't booked yet doesn't know their dealer or delivery date. A user picking up tomorrow does. One question upfront, where are you in the process, split the flow in two.
Cut the landing page at 1%
The call. Built a page to counter dealer myths before the flow even started. At 1% of traffic, 99% of users skipped straight past it. I cut it rather than carry it to everyone.
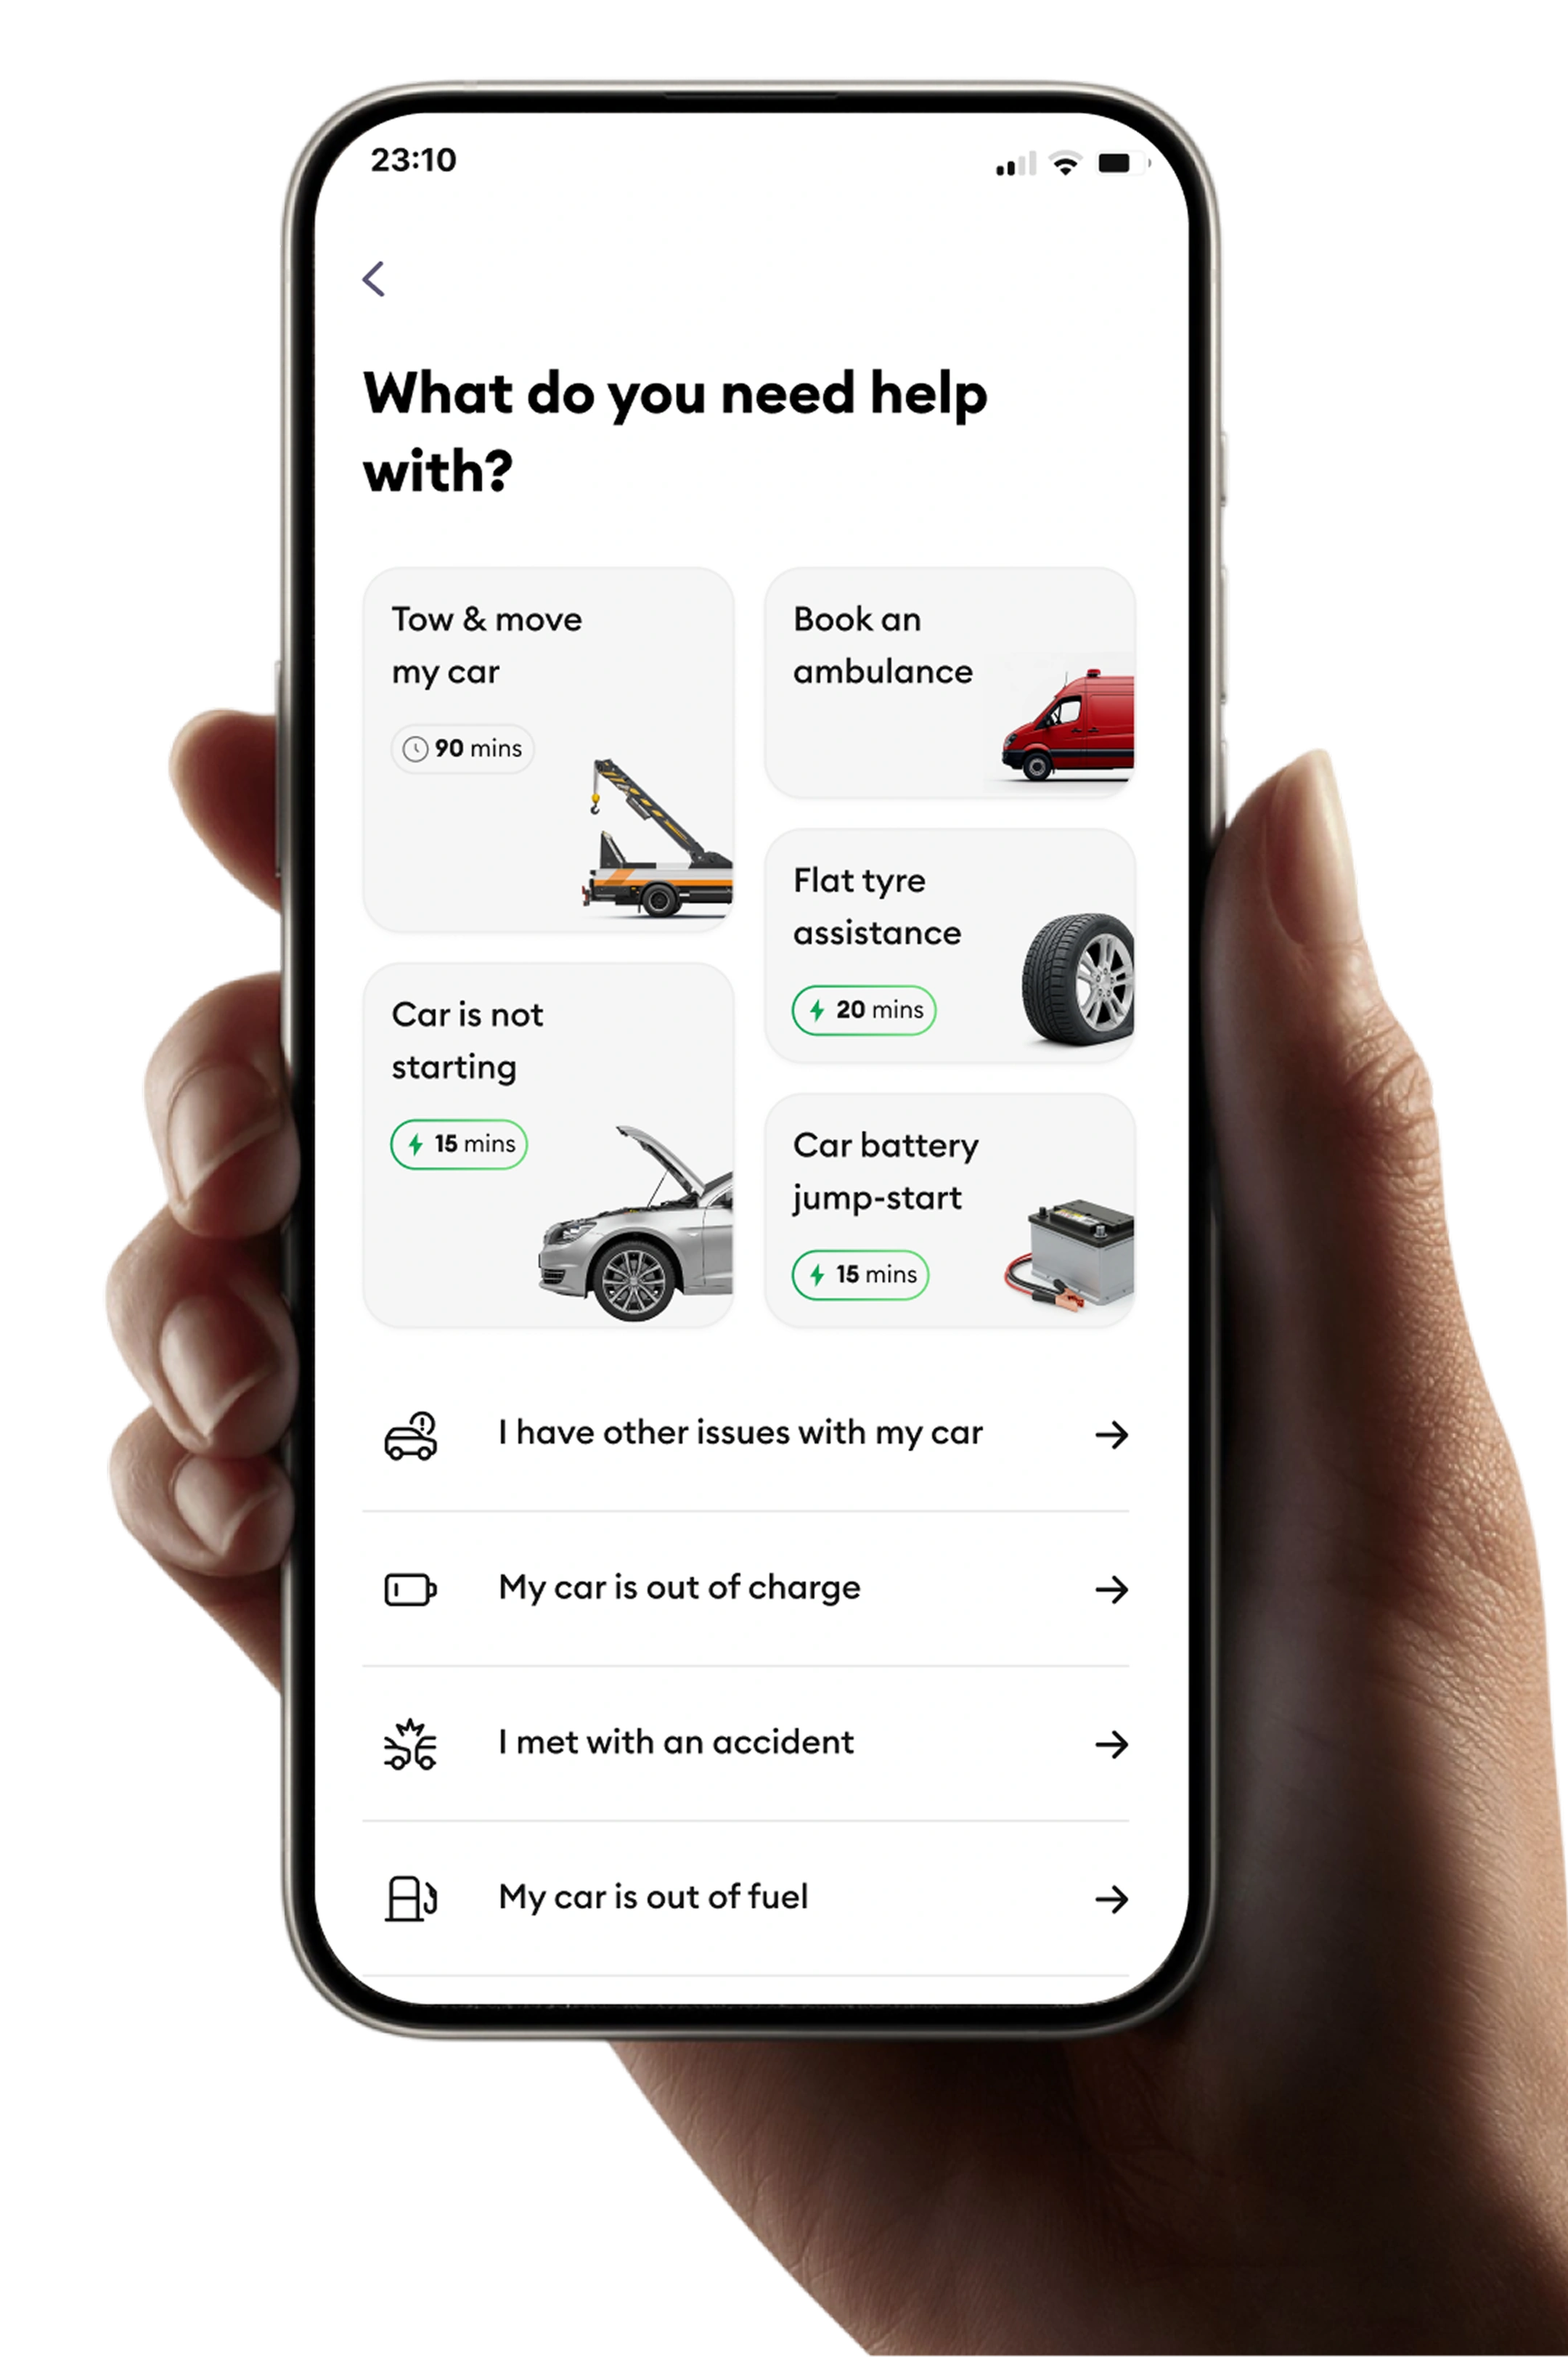
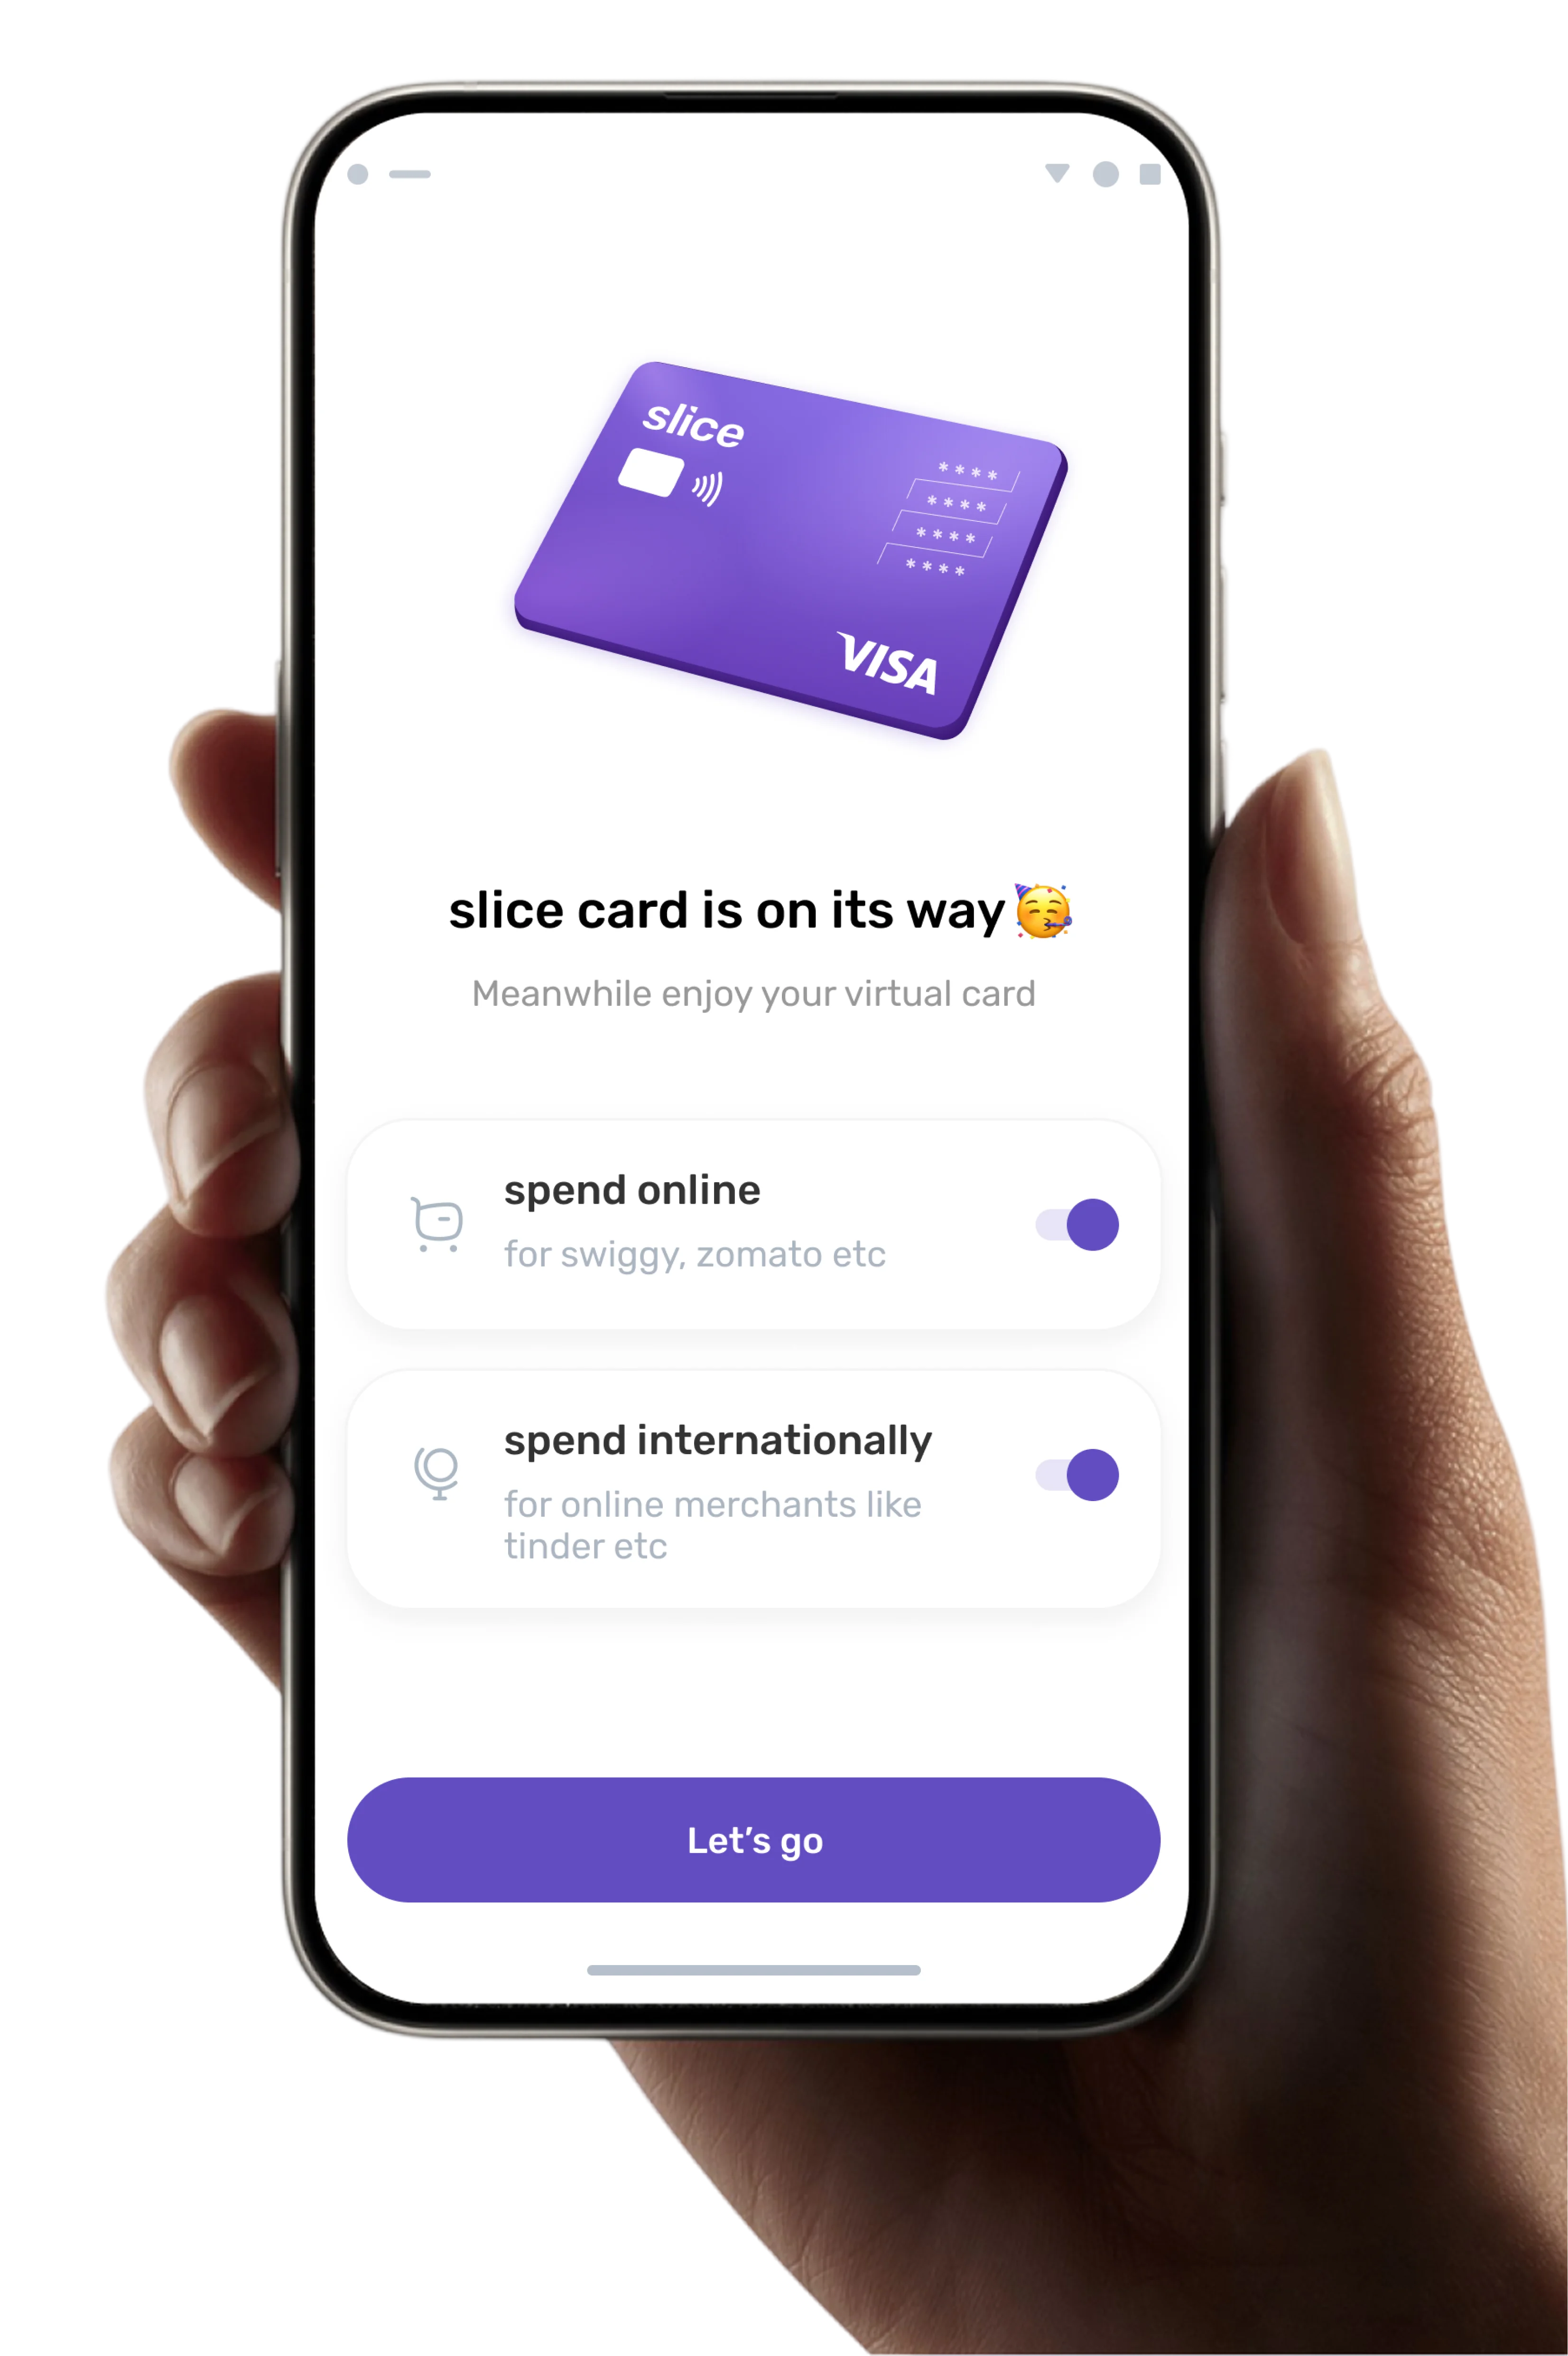
Key screens from the new car insurance journey: booking status entry, forked flows, plans page, dealer selection before payment, and checkout.


Three releases over three months. Each one had a question to answer and a decision to make, not just a traffic split.
The 1% stage was a small test group, its numbers moved around more than the later stages with far more users, so a dip there isn't a regression, it's a small sample finding its footing.
| Stage | When | What happened |
|---|---|---|
| 1% of users | February 2026 | The landing page barely got scrolled. We cut it and fixed a confusing plan name at the same time. |
| 50% of users | March 2026 | The new flow held up. Entry to quote crossed the old baseline for the first time. |
| 100% of users | April to May 2026 | Entry to quote settled between 59% and 65%. Mobile web, previously the weakest channel, caught up to about 55% entry to quote. |
Quote to sale held at around 5% through every stage of this project, and that's expected. It depends on when someone's car actually arrives, not on how good the journey is. Knowing what design can't fix is part of the job.
Two things I'd change if I ran this project again. Each would have moved us faster or taught us more.